Latin America is no longer one market with a few regulated exceptions. It is a patchwork of regulated markets, each with its own rules, payments and player habits. Working with operators across the region, we see five trends that will define who grows in 2027 and who stalls.
1. Regulation is now the default, not the exception
Peru, Brazil and Colombia have moved from grey markets to licensing regimes with real enforcement. Peru’s tax authority data shows remote sports betting and online games generated around S/ 209 million in taxes between January and November 2025. Brazil had 182 authorised betting brands in the first half of 2025, its first year of regulation. Colombia’s regulator, Coljuegos, collected 39% more in January–August 2026 than a year earlier, with online betting accounting for almost half.
For operators, this changes the question from “can we launch?” to “can our platform pass certification and report to the regulator from day one?” Technology choices are now regulatory choices.
2. One country, many rulebooks
Argentina shows where the region is heading. There is no national licence; each province regulates on its own terms. Mexico still has no standalone online licence and ties online operation to physical permits, while its gaming tax rose from 30% to 50% in 2026.
Operators that plan to expand need platforms that can be configured per jurisdiction — geolocation, identity checks, payment methods, limits and reporting — without rebuilding the stack every time they enter a new market.
3. Payments are local, and cash still matters
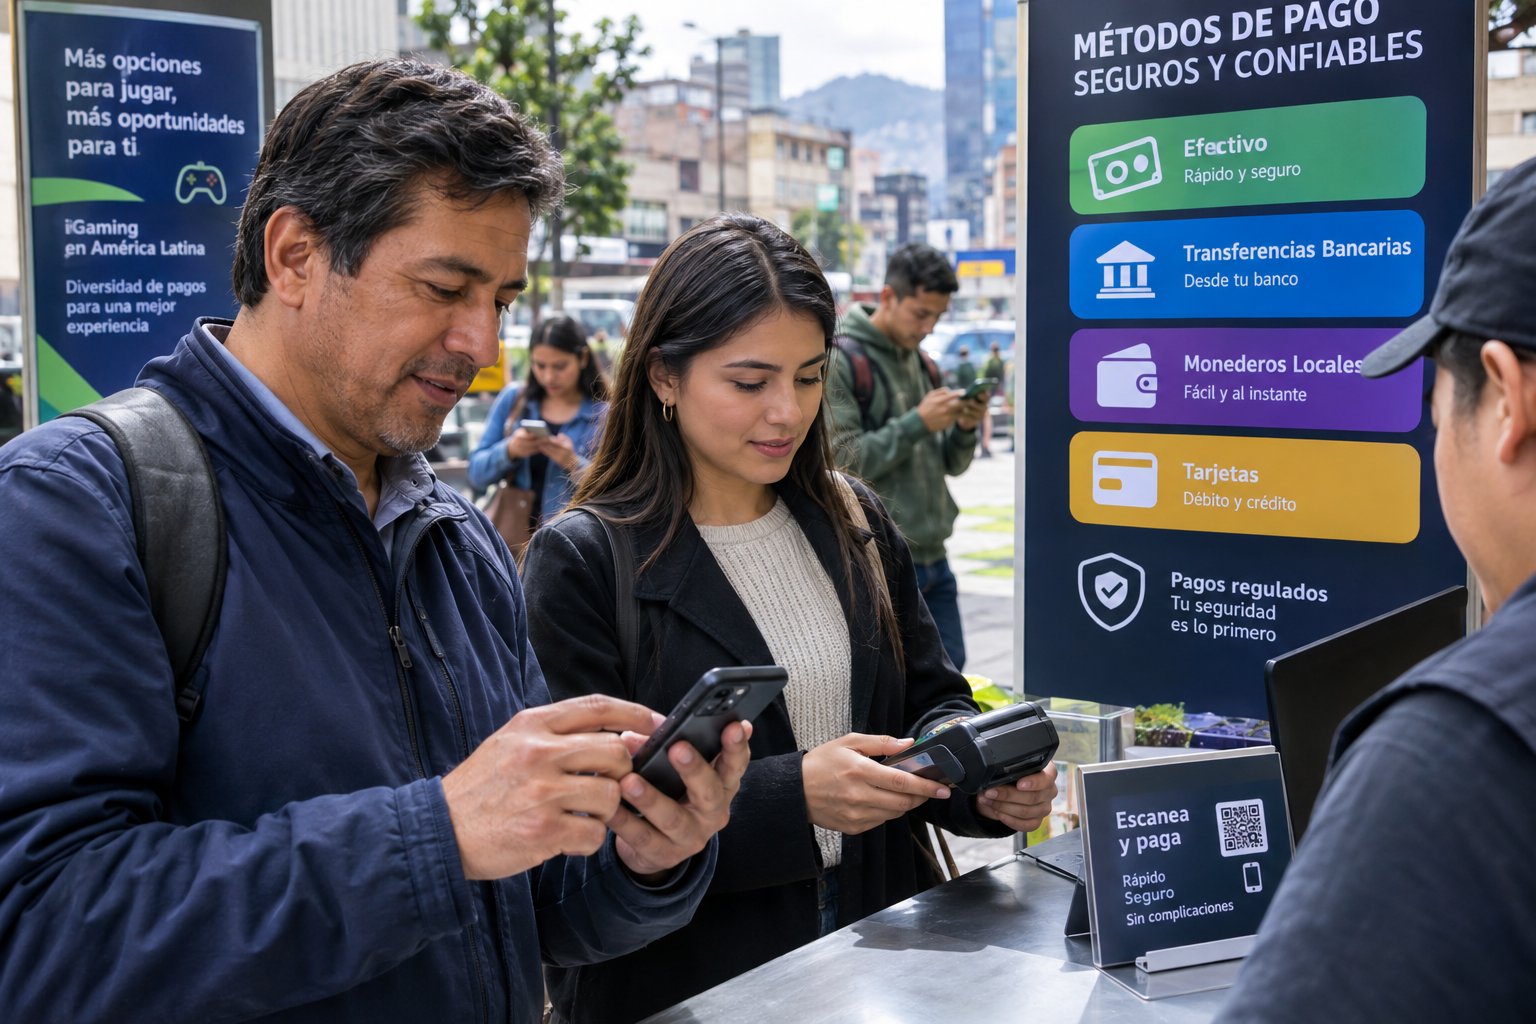
Cards are only part of the story. Cash deposit networks, bank transfers and local wallets drive conversion in many markets. Rules differ, too: Peru, for example, does not allow cryptocurrency for betting, while in Argentina some players use crypto and stablecoins to hedge against peso volatility. In one Argentine project, crypto made up about 62% of deposit volume in the first three months.
The winning payment mix is built country by country, not copied from Europe.
4. Agent networks are going digital
Retail betting shops and agent networks remain a core distribution channel in Latin America. The operators growing fastest are not abandoning them; they are connecting them to online products. Agent panels, commission tracking and cash-to-online deposit terminals let retail networks feed digital accounts instead of competing with them. We have seen agent-driven platforms in the region scale to tens of millions of players.
5. Casino and sportsbook on one platform
Football drives acquisition; casino drives retention. Operators running the two on separate systems pay twice for integrations and lose data between products. In 2027 we expect more operators to consolidate onto a single platform with a shared wallet, back office and player view, and to add content through one aggregation API rather than dozens of direct integrations.
What this means for operators
The common thread is flexibility under regulation. The platform has to adapt to each market’s rules, payments and channels, and it has to do so quickly, because licensing windows open and close.
At BSW, that is how we build: white label launches in around 35 days, custom turnkey platforms in about 12 weeks, and a single API with 150+ game providers for operators who already have a platform. We don’t issue local licences — those always belong to the operator — but we design the technology so that meeting the regulator’s requirements is part of the launch, not an afterthought.
Latin America rewards operators who treat compliance, payments and local habits as product decisions. In 2027, that will be the difference between launching and lasting.
